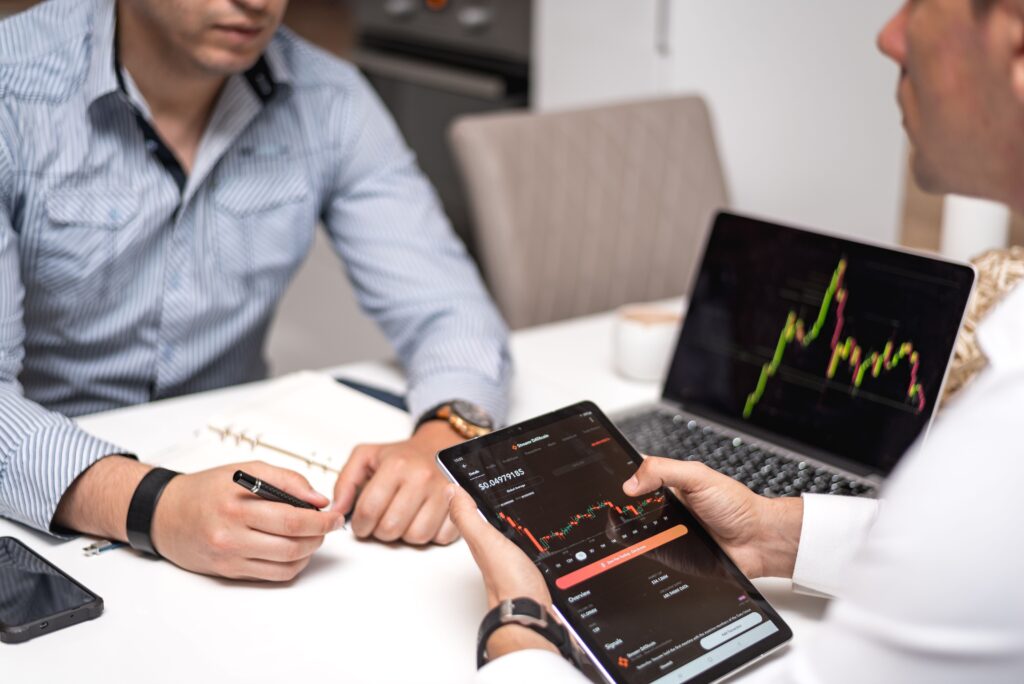
Colin Edsman has a small investment team working for him from his kitchen table. Alex scans the market for promising stocks and exchange-traded funds. Sarah checks his open positions before the close. Elena prepares a weekly performance report.
None of them are human. They are Claude AI agents, and Edsman, a stay-at-home dad and hairstylist profiled by The Wall Street Journal in September 2026, has given them enough autonomy to help manage a separate investment account at Robinhood. The arrangement is still experimental and comes with obvious risks, but it is a useful glimpse of where financial services are heading.
For the past few years, most of the conversation about AI in banking has focused on what institutions can automate: call centres, credit memos, compliance checks, fraud detection, marketing and back-office work. Those changes matter. But I suspect the more consequential shift may be happening on the other side of the counter.
The reality is that customers are getting their own technology too. And once AI can compare products, interpret financial information, monitor a customer’s position and increasingly act on their behalf, the competitive question changes. It is no longer simply which bank has the best app, or which broker has access to the widest panel. It becomes: who owns the relationship when the customer has an intelligent agent sitting between them and the financial system?
From advice to agency
The distinction between generative AI and agentic AI is important here. Generative AI gives you an answer. Agentic AI can take that answer and do something with it.
McKinsey has described a plausible retail-banking future in which a non-bank AI agent continuously scans the market for better savings rates, credit products and other financial opportunities, then executes transactions on the customer’s behalf. The customer might still hold deposits with a bank, but could rarely need to open the bank’s app, call its contact centre or visit a branch.
That scenario is no longer as remote as it sounds. McKinsey reported in April 2026 that 23 per cent of consumers in its global banking research were already using generative AI for financial tasks at least monthly. Among those users, common activities included understanding products, seeking investment advice and comparing alternatives. It also found 57 per cent of customers would consider using a third-party generative-AI financial agent if their bank did not offer one.
The shift from advice to action is what makes this strategically significant. A comparison site can tell you another bank has a better deposit rate. An agent could notice the difference, assess whether switching makes sense, prepare the move and eventually complete it with minimal involvement from you.
The friction that has historically protected customer inertia begins to disappear.
The bank may own the account but lose the customer
Digital banking once looked like disintermediation because customers stopped visiting branches. In reality, most banks simply moved the relationship onto a screen they still controlled. The branch became the app, but the interface remained the bank’s. Agentic AI threatens to break that link.
If a customer’s primary financial conversation happens with an independent AI assistant, the bank can remain essential infrastructure while becoming increasingly invisible. It may hold the money, provide the mortgage and carry the regulatory obligations, while somebody else’s technology decides when the customer sees its product and whether they stay.
That creates what I think of as a battle for the interface. Banks once competed for branch networks, then for app engagement. The next contest may be to remain visible to the intelligent layer sitting above both.
McKinsey has modelled what this could mean for deposits. Globally, enormous amounts of money sit in transaction and low-interest accounts partly because people value convenience and rarely optimise every dollar. An agent that continuously scans yields and sweeps idle cash towards better returns can turn that inertia into a much more contestable market. McKinsey estimates that if only 5 to 10 per cent of checking balances moved into higher-yield accounts, industry deposit profits could fall by 20 per cent or more. That is scenario analysis rather than a forecast, but it makes the economic pressure clear.
The bank of the future may therefore need to appeal not only to a person, but to the person’s agent. Product data needs to be machine-readable. Offers need to be easy to compare. Onboarding and switching need to work through APIs. Marketing may increasingly need to influence an algorithm that has no emotional attachment to a brand and is perfectly willing to move when the numbers change.
Loyalty was already weakening
AI is not creating this fluidity from scratch. Customer behaviour was moving in that direction already, particularly among younger Australians.
Finder survey data reported by The Sydney Morning Herald in late 2025 found 18 per cent of Gen Z respondents had switched their savings account in the previous six months, compared with 7 per cent of Gen X and 4 per cent of Baby Boomers. UBank told the paper that younger customers were more likely to maintain relationships with multiple financial providers rather than treat one bank as their financial home.
The more striking finding comes from ASIC’s 2026 Moneysmart research. Among Australians aged 18 to 28, 18 per cent were already using AI platforms for financial information or guidance, while 64 per cent said they trusted AI platforms for that purpose. Nearly two-thirds also said they were confident in the accuracy and appropriateness of AI-provided financial guidance.
That level of trust deserves some caution. ASIC itself warned that general-purpose AI tools can provide incomplete, inappropriate or misleading financial guidance. But the behavioural signal is difficult to ignore. The generation entering its prime borrowing, investing and earning years is less loyal to institutions and more comfortable seeking financial guidance from technology.
Put those two trends together and switching becomes easier at exactly the moment attachment becomes weaker.
Why the rise of AI may strengthen the case for brokers
There is a fascinating Australian counterpoint to all of this. If digital technology were simply removing the need for financial intermediaries, mortgage brokers should be losing ground. They are doing the opposite.
Mortgage brokers facilitated a record 81.6 per cent of all new residential home lending in Australia in the June 2026 quarter, according to Cotality data commissioned by the Mortgage & Finance Association of Australia. Eight years earlier, the figure was 53.9 per cent.
The longer-term Deloitte and MFAA research helps explain why. The broker’s role has moved well beyond comparing interest rates and filling out applications. Surveyed brokers were accredited with an average of 23 lenders and could access as many as 65 through aggregator panels, but their value proposition increasingly includes education, policy navigation, proactive repricing and ongoing support. In the 2025 report, 72 per cent of broker business came from repeat customers and customer referrals.
That matters because access to information is precisely the part of the proposition AI is commoditising fastest.
A borrower does not need a broker simply because mortgage rates are hard to find. They need help because lending remains consequential, rules differ between lenders, personal circumstances rarely fit neatly into a comparison table and the cost of getting a major decision wrong can last for years.
One Melbourne broker described to me how he handles rate changes with clients. He cannot call a thousand people every time the market moves, and many younger clients do not particularly want a phone call anyway. Instead, he records short, low-pressure voice messages that clients can listen to when it suits them. He can create 10 or 15 in around 20 minutes, but the interaction still feels personal.
I like that example because it avoids a false choice between high-tech and high-touch. Technology is being used to scale the relationship rather than remove it.
Even consumer platforms are beginning to present the choice this way. Australian mortgage comparison service Craggle places ‘Chat with Craggle AI’ beside ‘Speak with a Broker’ on its website. That may be a surprisingly good picture of where this market is heading: machine assistance and human judgement sitting side by side rather than one cleanly replacing the other.
When information becomes abundant, interpretation becomes scarce
For most of financial-services history, information asymmetry created value. Institutions knew more than customers about products, pricing, policy, risk and process. Intermediaries earned their place partly by helping people access and navigate that knowledge. What’s becoming increasingly clear is that AI dramatically narrows that gap.
A capable model can read product documents, summarise lending policies, compare features and model scenarios in seconds. Agentic systems can go further by gathering documents, drafting communications and orchestrating parts of the application process. McKinsey’s commercial-credit research found banks already exploring AI for early-warning systems, credit memo drafting, credit assessment and customer engagement, although full deployment remains relatively limited and many institutions are still wrestling with accuracy, validation and governance. So the value does not disappear. It migrates.
When information becomes abundant, interpretation becomes scarce. Knowing what a policy says matters less than understanding how it applies to this customer, in this situation, with these trade-offs. Producing an answer matters less than knowing whether it should be trusted. Finding three technically suitable products matters less than explaining which compromise is worth making.
This is where the strongest human advisers may become more valuable, not less. Their advantage will not be that they can remember more product information than a machine. It will be that they understand context, recognise when something does not add up, take responsibility for a recommendation and can have the difficult conversation when there is no perfect answer.
The future broker may therefore look less like an information intermediary and more like a trust intermediary.
AI is creating an arms race in trust
There is another reason trust matters more in an AI-enabled financial system: the same technology that helps institutions analyse and verify information is making deception cheaper.
In August 2026, AUSTRAC’s Fintel Alliance announced that analysis involving ten major Australian banks had identified potentially hundreds of millions of dollars in suspected fraudulent mortgage loans. The cases included inflated incomes, misrepresented employment, fabricated or unverifiable business activity and complex funding arrangements.
Synthetic documents raise the stakes further. If payslips, statements and business records can be generated or manipulated convincingly at trivial cost, checking whether a document looks legitimate becomes a weaker defence. The direction of travel is towards verification at source: trusted data feeds, consent-based access, digital identity, better provenance and automated anomaly detection.
This creates an arms race. AI can help criminals fabricate evidence while helping lenders detect patterns that would be almost impossible for a human team to see. Banks can automate KYC and fraud monitoring, but they also inherit new risks around model errors, bias, cyberattacks and autonomous decision-making.
McKinsey’s work on the future of risk makes the human role here quite clear. As routine monitoring becomes more automated, it argues that critical thinking, intellectual curiosity and the ability to ask the right ‘what if?’ questions become more important. The human in the loop shifts from performing every control to overseeing the system and intervening when something falls outside the pattern.
That is a useful principle well beyond risk. The more we automate financial decisions, the more valuable good judgement becomes at the exceptions.
The new intermediary
The financial-services industry has spent years trying to remove friction. AI may finally remove more of it than anyone expected.
That is good news for customers in many ways. It could mean faster applications, better product matching, earlier warnings, lower administrative costs and much less tolerance for institutions relying on customer inertia. It may also give smaller lenders a better chance to compete. APRA’s 2025 review of small and medium-sized banks noted that digitisation and changing customer preferences are already reshaping the competitive environment, while high fixed costs continue to weigh more heavily on smaller institutions.
But removing friction does not remove the need for intermediation. It changes the intermediary. Sometimes it will be an AI agent that knows the customer’s financial life, scans the market continuously and handles routine decisions. Sometimes it will be a human broker or banker using AI behind the scenes to work faster and see more. Increasingly, it may be a combination of the two.
For banks, this means the strategic challenge is larger than deploying better AI internally. They need to consider how their products remain discoverable, attractive and trusted when an external agent becomes the customer’s gateway to finance.
For brokers, the warning is equally clear. The shallow version of broking – information retrieval, product comparison and paperwork – is becoming easier to automate. The deeper version – judgement, accountability, education, reassurance and understanding a person well enough to know what matters to them – becomes the part worth strengthening.
The bank may still own the account. The lender may still own the mortgage. But neither can assume they own the customer relationship. In an age when everyone has access to more information than they can possibly process, the scarce asset will not be information at all.
It will be trust in whoever helps us decide what to do with it.
Michael McQueen is a globally recognised trend forecaster, change strategist and keynote speaker.
A bestselling author of 10 books, Michael’s latest release was named by Malcolm Gladwell and Adam Grant as one of the top five must-read new leadership books. He is a sought-after media commentator, with his insights regularly featured in Forbes, The Guardian, and CNN.
To find out more about Michael and his work, click here.
NOTES
Lang, Hannah Erin. ‘He’s Letting AI Agents Invest His Money. They Even Have Names.’ The Wall Street Journal, September 5, 2026. https://www.wsj.com/tech/ai/the-ai-shift-turning-everyday-investors-into-mini-quant-funds-ebe4d45f.
Imregun, Darius, David Tan, Marukel Nunez Maxwell, Max Floetotto, Muthanna Muslet, Russell Shore, and Sergey Khon. ‘How Gen AI Agents Threaten Retail Banks’ Customer Relationships.’ McKinsey & Company, April 30, 2026. https://www.mckinsey.com/industries/financial-services/our-insights/how-gen-ai-agents-threaten-retail-banks-customer-relationships.
Segev, Ido, and Roberta Fusaro. ‘Move First or Fall Behind: How AI Is Rewriting the Rules of Banking.’ The McKinsey Podcast, May 28, 2026. https://www.mckinsey.com/industries/financial-services/our-insights/move-first-or-fall-behind-how-ai-is-rewriting-the-rules-of-banking.
Australian Securities and Investments Commission. ‘ASIC Moneysmart Gen Z Financial Behaviours Report 2026.’ 2026. https://download.asic.gov.au/media/3l1l0xpc/26-049mr-asic-moneysmart-gen-z-financial-behaviours-report-2026.pdf.
Yeates, Clancy. ‘The Disloyal Generation That Has Banks Scratching Their Heads.’ The Sydney Morning Herald, December 29, 2025. https://www.smh.com.au/business/banking-and-finance/the-disloyal-generation-that-has-banks-scratching-their-heads-20251212-p5nn5o.html.
Mortgage & Finance Association of Australia. ‘Mortgage Broker Market Share Reaches Record 81.6%.’ September 3, 2026. https://www.mfaa.com.au/news/mortgage-broker-market-share-reaches-record-81-6.
Deloitte Access Economics. The Value of Mortgage and Finance Broking 2025. Mortgage & Finance Association of Australia, February 10, 2025.
Govindarajan, Arvind, Jania Kesarwani, Filippo Maggi, Kevin Buehler, and Maria Acuna. ‘Banking on Gen AI in the Credit Business: The Route to Value Creation.’ McKinsey & Company, July 8, 2025. https://www.mckinsey.com/capabilities/risk-and-resilience/our-insights/banking-on-gen-ai-in-the-credit-business-the-route-to-value-creation.
AUSTRAC. ‘Fintel Alliance Uncovers Coordinated Mortgage Fraud Across Major Lenders.’ August 19, 2026. https://www.austrac.gov.au/news-and-media/media-release/fintel-alliance-uncovers-coordinated-mortgage-fraud-across-major-lenders.
Raufuss, Anke, Arvind Govindarajan, Ida Kristensen, and Thomas Kelepouris. ‘The Future of Risk: How Global Trends Are Reshaping Risk Management.’ McKinsey & Company, December 17, 2025. https://www.mckinsey.com/capabilities/risk-and-resilience/our-insights/the-future-of-risk-how-global-trends-are-reshaping-risk-management.
Australian Prudential Regulation Authority. ‘APRA’s Plans to Support Small and Medium-Sized Banks.’ October 30, 2025. https://www.apra.gov.au/news-and-publications/apras-plans-to-support-small-and-medium-sized-banks.